Why Your Home's Price and Its Insurance Coverage Aren't the Same Number
Should my home insurance match what I paid for my house? No. Your dwelling coverage should reflect what it would cost to rebuild your home, not its market value or purchase price. In the St. Louis Metro Area, those two numbers can be very different.
Here's a question I hear from buyers all the time once we're under contract and they start shopping for homeowners insurance: "Shouldn't my coverage just match the purchase price?"
It's one of the most common misunderstandings in the whole home buying process, and I get why. The purchase price is the biggest number you've been staring at for weeks. But insurance doesn't care what you paid. It cares what it would cost to rebuild your home from the ground up if the worst happened.
In West St. Louis County and the St. Louis Metro Area, that difference can work for you or against you, depending on where you buy and how old the house is. Let's walk through it.
Market Value vs. Replacement Cost: What's the Difference?
These are two completely different ways of measuring a home.
- Market value is what a buyer would pay for your home today. It includes the land, the location, the neighborhood, and current demand.
- Replacement cost is what it would take to rebuild your home with materials of similar kind and quality at today's labor and construction prices. It does not include the land.
That last part is the key. If a fire or a storm destroys your house, the lot is still there. You're insuring the structure, not the dirt it sits on.
When Rebuild Cost Is Lower Than Market Value
In some of the St. Louis Metro Area's most desirable communities, a large share of a home's value comes from the land and the location. Think about Ladue (63124), Clayton (63105), and parts of Creve Coeur (63141), where lot size, walkability, and address drive prices.
In those areas, the cost to rebuild the house itself can be well below what you paid. Insuring for the full purchase price may mean paying for coverage you could never actually collect.
When Rebuild Cost Is Higher Than Market Value
This is the one that catches people off guard, and it matters a lot in the neighborhoods I work in every day.
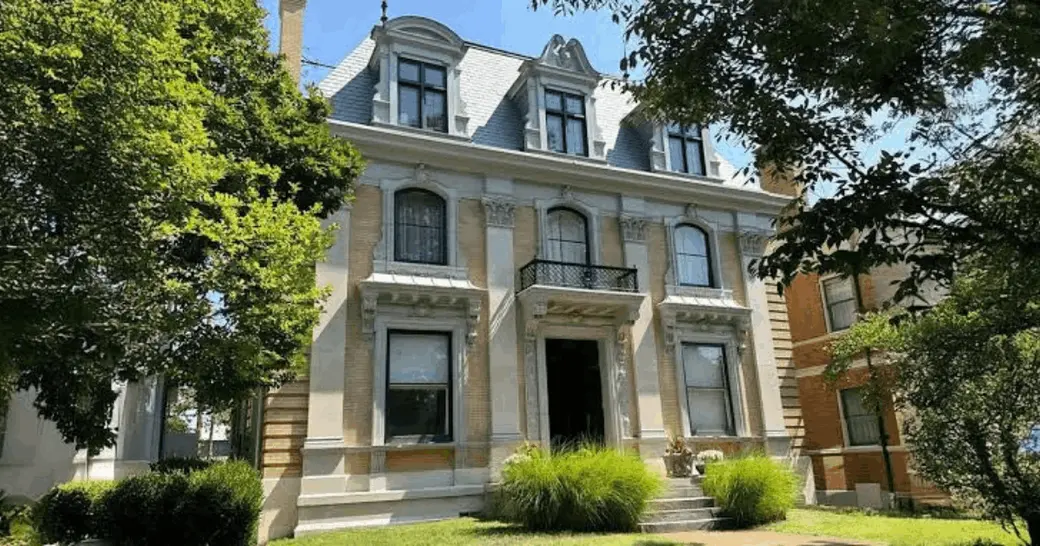
Older homes in Kirkwood (63122), Webster Groves (63119), University City (63130), and the Central West End (63108) are full of details that are expensive to recreate today:
- Plaster walls and ceilings
- Custom millwork, built-ins, and original trim
- Slate or clay tile roofs
- Solid brick construction
- Leaded and stained glass
- Hardwood floors and decorative tile
A beautiful 1920s home might sell for a price that looks reasonable on paper, while the cost to rebuild it with similar craftsmanship could be significantly higher. If your coverage is based on the purchase price, you could be underinsured without realizing it.
Replacement Cost vs. Actual Cash Value
Once you know how much coverage you need, the next question is how your policy pays out. According to the National Association of Insurance Commissioners, there are two main approaches:
- Replacement cost pays to repair or replace damaged property with new materials of similar kind and quality, without subtracting for age.
- Actual cash value pays the replacement cost minus depreciation. In other words, you get what the damaged item was worth at the time, not what it costs to replace it new.
That difference can be dramatic. An actual cash value policy on a 15-year-old roof may pay a fraction of what a new roof actually costs.
Why the roof deserves extra attention in St. Louis
The St. Louis Metro Area gets its share of hail and severe spring storms, and roofs take the hit. Some policies treat roofs differently than the rest of the house, paying on an actual cash value basis once a roof reaches a certain age, or carrying a separate wind and hail deductible.
When I'm working with buyers, the age and condition of the roof is always part of the conversation, and it's worth asking your insurance agent exactly how your policy handles roof claims before you close.
The Coverage Older Homes Often Need: Ordinance or Law
Here's a detail most buyers have never heard of. If an older home is damaged, the rebuild typically has to meet today's building codes. That can mean updated electrical, plumbing, egress windows, or structural requirements the original home never had.
Standard policies often limit how much they'll pay toward those code-required upgrades. Ordinance or law coverage helps cover that gap. If you're buying an older home in Webster Groves, Kirkwood, University City, or a historic street in the Central West End, it's a question worth raising with your agent.
4 Questions to Ask Your Insurance Agent Before You Close
I'm not an insurance agent, and I always tell my clients to talk to a licensed professional about their specific policy. But these are the questions I encourage every buyer to ask:
- How did you calculate my dwelling coverage amount? Make sure it's based on rebuild cost, not the purchase price.
- Is my policy replacement cost or actual cash value? Ask about the dwelling, your personal property, and the roof separately.
- Do I have extended or guaranteed replacement cost? Some policies add a cushion above your coverage limit in case rebuilding costs more than expected.
- Do I have ordinance or law coverage, and how much? This is especially important for older homes.
The Missouri Department of Commerce and Insurance also has helpful consumer resources on home insurance if you want to read more before you shop.
Why This Matters Before Closing
Homeowners insurance is typically required by your lender before closing, so you'll be shopping for it during a busy stretch of your transaction. Starting early gives you time to compare quotes, ask the right questions, and avoid any last-minute surprises, especially with older homes or roofs near the end of their life.
It's one of those details that doesn't feel urgent until it suddenly is, and I'd much rather my buyers go in with their eyes open.
Frequently Asked Questions
Should my homeowners insurance match my purchase price? No. Your dwelling coverage should be based on what it would cost to rebuild your home, not what you paid for it. Market value includes the land and location, which do not need to be rebuilt after a loss.
What is the difference between replacement cost and actual cash value? Replacement cost pays to repair or replace damaged property with new materials of similar kind and quality. Actual cash value pays the replacement cost minus depreciation, so older items like roofs may receive much lower payouts.
Do older homes in St. Louis need special insurance coverage? Older homes often cost more to rebuild because of features like plaster, custom millwork, and brick, and repairs may need to meet current building codes. Buyers of older homes should ask their insurance agent about extended replacement cost and ordinance or law coverage.
Let's Talk Before You Buy
Buying a home in Kirkwood, Webster Groves, the Central West End, or anywhere in West St. Louis County comes with a lot of details, and insurance is one of the easiest to overlook. When you work with me, you get me, and I'll make sure these questions come up early, not the week before closing.
If you're starting to think about buying in the St. Louis Metro Area, let's connect at shariwhay.com. I would love to help you find your Whay home.
Helping you find your Whay home, Shari Whay, REALTOR® Real Broker LLC St. Louis Metro Area | West St. Louis County
Categories
- All Blogs (38)
- 63130 (1)
- Best Realtor (1)
- Buyer Resources (13)
- Buying, Selling & Relocation (16)
- Central West End Neighborhood Guide (4)
- Chesterfield Home Buyers (5)
- Chesterfield Home Sellers (2)
- Chesterfield Real Estate (6)
- Clayton Neighborhood Guide (2)
- Creve Coeur Real Estate Guide (1)
- Events/Things to Do (1)
- Historic and Luxury Homes (11)
- kirkwood (3)
- Kirkwood Real Estate (1)
- kirkwood school district (4)
- Ladue MO Real Estate (2)
- Ladue Neighborhood Guide (1)
- Living in 63017 (2)
- Living in 63105 (3)
- Living in 63108 (3)
- Living in 63119 (2)
- Living in 63122 (3)
- Living in 63124 (3)
- Luxury Condominiums (3)
- Market Insights & Real Estate Trends (10)
- Market Updates (2)
- Market Updates, Kirkwood, Sellers, Buyers (5)
- Move-Up Buyers (5)
- Neighborhood Guides (5)
- relocating (2)
- Relocating to St. Louis (13)
- Seller Resources (9)
- St. Louis Luxury Real Estate (10)
- St. Louis Neighborhoods Guide (13)
- University City Real Estate Guide (1)
- West County Living (11)
- West St. Louis County (10)
Recent Posts